

Google Wallet
by Google LLC
4.4
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.4
- Price
- Free
- Download
- 1.00B
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
 Analysis by Getfullapps
I use Google Wallet as a way to keep the small but important items I normally carry in my physical wallet in one place. Its most useful idea is simple: instead of searching through a crowded pocket or bag, I can open one app when I need a payment card, pass, or ticket. That sounds modest, but the difference becomes obvious when I am standing at a checkout or moving through a busy station.
This is a free finance app from Google LLC, available for users aged Everyone. It has been around since June 24, 2011, and its broad availability is reflected in its reach: more than one billion installs and an average rating of 4.4 from roughly 2.2 million ratings. Those figures do not automatically make it right for everyone, but they do match my impression that Wallet is designed as a practical everyday tool rather than a specialist banking product.
Why keeping cards, passes, and tickets together matters
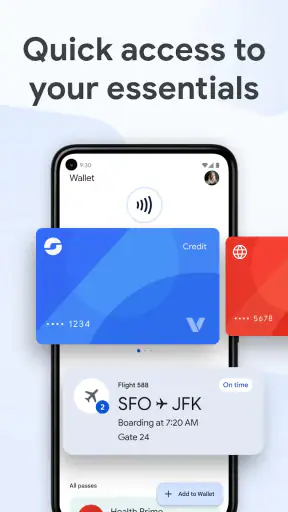
The capability I value most is the central wallet view. Google Wallet brings together digital versions of everyday items that are otherwise easy to misplace: payment cards, travel or event passes, and tickets. The benefit is not that it replaces every physical document. The benefit is that it reduces the number of places I need to check before leaving home or completing a purchase.
Stories Featuring Google Wallet
I find this especially useful when my physical wallet is already full. A loyalty card or ticket that I use only occasionally does not need to take up space every day. I can keep the digital version available and leave the physical card somewhere safe. That makes the app more useful than a simple payment shortcut because it helps organize the wider collection of things I might need while I am away from home.
There is also a mental advantage. When I know that the relevant item should be inside Wallet, I do not have to remember which email, message, photo, or pocket contains it. That reduction in searching is the real effect of the app. It turns a scattered set of digital items into a single place with a clear purpose.
The strongest reason to use Google Wallet is not novelty; it is fewer interruptions during ordinary errands. I can think about the checkout, the train platform, or the venue entrance instead of managing several unrelated apps. For someone who regularly carries multiple cards and tickets, that small improvement can become a dependable part of the daily routine.
What the app is, and what it is not
It is important to approach Wallet as a container and access point, not as a replacement for a bank. It belongs to the finance category, but I would not use it to analyze spending, manage a budget, or replace the full app provided by my bank. Those jobs still belong to banking and personal-finance tools.
Articles to Explore Next

Ludo King and the Social Life of a Lucky Six
Hill Climb Racing and the Mobile Racing Rules That Last
Unlocking the Power of Facebook Groups for Community Building
Why iTunes Is Finding Its Way Back
Google Play Store Gets the Basics Right, Until Its Crowded Menus Get in the Way
Why Fortnite Still Owns the Conversation
Wallet is better at the moment of use. It helps me present the right card or pass when I need it. If I want detailed transaction history, account controls, a dispute process, or broader money management, I would go to the relevant bank or service instead. Understanding that boundary prevents disappointment and makes the app easier to judge fairly.
How I set up a useful wallet
My advice is to begin with the items I genuinely use rather than trying to transfer every card at once. Adding a main payment card first lets me learn the flow without creating a cluttered collection. After that, I would add the passes and tickets that are likely to be needed away from home.
Organization matters more than people expect. A wallet full of expired event tickets or old passes can recreate the same searching problem as a physical wallet stuffed with receipts. I periodically remove items that are no longer relevant and keep the list focused on current needs. This is one of the simplest ways to make the app feel faster, even without changing any settings.
I also recommend checking an item before an important trip or event. A ticket saved days earlier may be easy to find, but I prefer opening it once before leaving so I know where it appears and can confirm that the information is readable. That habit is more valuable than waiting until I am at an entrance with a queue behind me.
For payment cards, I treat the setup as something to verify carefully rather than rush. The card must be the one I intend to use, and I want to know which card is selected before I reach the terminal. This avoids a surprisingly common kind of friction: the app works, but I have not prepared it in the way that suits my spending habits.
A realistic checkout routine
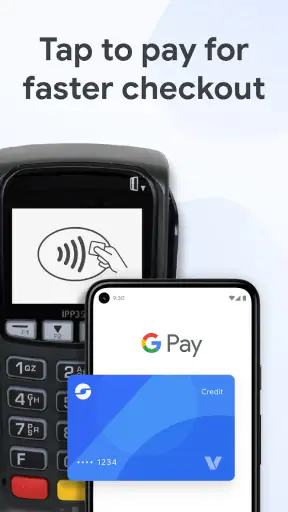
Imagine I am buying groceries after work with my physical wallet at home. I open Wallet, choose the card I prepared, and use the phone at the payment terminal. The practical advantage is not merely avoiding a plastic card. I also avoid searching through a bag, remembering which card is active, or discovering that the card I brought is not the one I wanted.
That routine is most comfortable when I prepare before reaching the counter. I do not want to stand there scrolling through unrelated passes or trying to decide which card to use while other customers wait. A few seconds spent becoming familiar with the wallet view makes the actual payment feel much more natural.
There is a useful trade-off here. A digital wallet can be quicker than a physical one, but only when it is maintained. If I add everything and never clean it up, the app becomes a digital junk drawer. If I keep only current items, the single-location approach works as intended.
Using it for travel and events
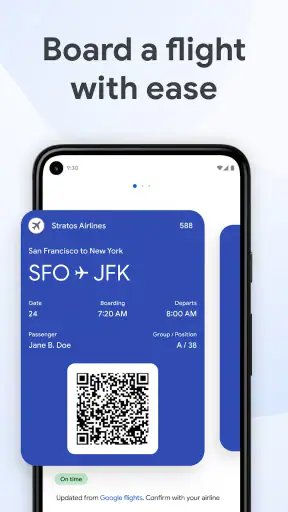
Travel is where the collection concept becomes more convincing. Instead of switching between an email account, a browser, screenshots, and a separate ticket app, I can place the relevant digital items in Wallet when the service supports them. I still keep important travel information elsewhere when necessary, but having the pass close at hand reduces the number of steps during a rushed transfer.
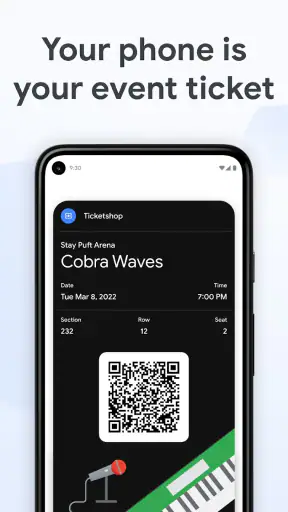
The same applies to events. At an entrance, the problem is usually not understanding the ticket; it is finding it quickly and displaying it without fumbling. Wallet gives that ticket a predictable home. I find that especially helpful when my phone contains many notifications and messages, because I do not have to search through a conversation to locate the item I need.
One practical tip is to avoid relying on a last-minute screenshot as the main plan when a proper wallet entry is available. A screenshot may be difficult to locate and may not behave like an interactive pass. Keeping the official digital item in its intended place is a cleaner workflow, while retaining any necessary backup information separately.
Where the experience can become less smooth
Google Wallet cannot make every card, pass, or ticket behave identically. The usefulness of a digital item depends partly on the service that issued it. Some items may be easy to add and use, while others may still require the issuer’s own application or a physical version. That means I see Wallet as a central organizer, not a guarantee that every document can be imported.
This is also why I would not discard an essential physical card immediately after adding a digital one. For routine purchases, the phone may be convenient. For travel, emergencies, or situations where a device is unavailable, a physical backup can still be sensible. The app reduces what I need to carry, but it does not remove every reason to carry something physical.
Another limitation is that a single app does not eliminate the need for account security. A phone containing payment cards and tickets deserves the same care as a physical wallet. I keep the device protected and avoid treating the convenience of quick access as permission to be careless. The fewer objects I carry, the more important the remaining access point becomes.
Some people may also dislike the idea of putting too many important items into one digital location. I understand that concern. The concentration is convenient, but it creates a dependency on the phone and on the services connected to the items. If that trade-off makes you uncomfortable, a physical wallet or a mixture of physical and digital cards may be the better choice.
How it compares with the usual alternatives
The obvious alternative is a traditional wallet. A physical wallet is dependable in situations where a phone is unavailable, and it does not require searching through a screen. It can also feel faster for someone who uses only one or two cards. Google Wallet is more attractive when I want to reduce bulk, keep occasional cards accessible, or bring tickets and passes together with payment items.
Another alternative is using each issuer’s separate app. That approach may offer more detail about a specific card or ticket, and it can be the right choice when the issuer provides controls that Wallet does not. The downside is fragmentation. I may need to remember which app contains which item, sign in repeatedly, or search through different interfaces during the same day.
There is also the option of storing tickets in email or as screenshots. That can work in a pinch, but it is less organized and more dependent on remembering where the file or message is located. Wallet’s advantage is the predictable destination. Its weakness is that the experience still depends on whether the issuer supports the relevant digital format.
For detailed financial management, a banking app is clearly stronger. I would choose the bank’s app for reviewing transactions, controlling an account, or handling account-specific issues. I would choose Wallet for presenting a card or pass quickly. The two tools complement each other better than they compete.
Who will benefit most from it
I think Google Wallet is a strong fit for people who use several payment cards, attend events, travel often, or dislike carrying a thick physical wallet. It is also useful for anyone who frequently loses time searching through messages and email for a ticket. The more varied your everyday digital items are, the more value you get from giving them one recognizable home.
It suits people who prefer a straightforward routine. Add the current items, remove expired ones, and open the app when a card or pass is needed. I do not think it requires constant attention, but it rewards a little maintenance. That is a fair exchange for the convenience it provides.
I would be more cautious about recommending it to someone who wants a full personal-finance dashboard, relies heavily on issuer-specific account features, or strongly prefers physical cards. It is also not the right sole solution for someone who cannot depend on a phone during important journeys. In those cases, a banking app, an issuer’s app, or a physical backup may be more appropriate.
The app is free, supports a minimum operating system of Android 9, and is rated for Everyone. Those details make it approachable for a broad range of users, although the practical experience still depends on the phone, the card issuer, and the services behind each pass. I would check compatibility with the items I actually use before reorganizing my entire wallet around it.
My recommendation after regular use
After using Google Wallet as a daily organizer, I see its value in the moments that usually seem too small to matter: finding a ticket without searching, choosing the right card before a purchase, or leaving an occasional loyalty card at home without losing access to it. The app does not try to solve every financial task, and that narrow focus is part of its appeal.
My recommendation is to use it selectively. Start with one payment card and one or two current passes, learn the routine, and keep the collection tidy. Maintain a sensible physical backup for situations where a phone is not enough. Used that way, Google Wallet becomes a practical bridge between a traditional wallet and the scattered digital items already living on a phone.
For me, the deciding question is simple: do I regularly need several cards, tickets, or passes while away from home? If the answer is yes, the app can remove genuine friction from everyday errands. If the answer is no, a physical card or a bank’s own app may already do the job with fewer moving parts. That makes Wallet an easy recommendation for the right routine, but not a requirement for everyone.
Pros
- Simple and intuitive interface.
- Secure transactions with encryption.
- Integrates with multiple services.
- Fast and reliable payment processing.
- Supports loyalty and gift cards.
Cons
- Limited support for some banks.
- Requires internet connection.
- Not available in all countries.
- May have occasional app glitches.
- Some features limited to regions.
FAQs for Google Wallet
What is Google Wallet used for?
Google Wallet is a digital payment platform that allows users to store and manage their payment information securely. It enables contactless payments using NFC technology, sending and receiving money, and storing loyalty cards and tickets. This makes transactions more convenient and reduces the need to carry physical cards.
Is Google Wallet secure to use?
Yes, Google Wallet employs multiple layers of security to protect users' financial information. It uses encryption and tokenization to safeguard data, and transactions require authentication via PIN, fingerprint, or facial recognition. Additionally, Google monitors accounts for suspicious activity to prevent fraud.
Can Google Wallet be used internationally?
Google Wallet can be used in many countries for sending and receiving money or making payments where Google Pay is accepted. However, availability may vary based on your location, and certain features might be restricted in some regions. It's best to check the local availability before traveling.
What devices are compatible with Google Wallet?
Google Wallet is compatible with most Android devices running Android 5.0 (Lollipop) or higher and iOS devices. Ensure your device supports NFC for contactless payments. You can download the app from the Google Play Store or the Apple App Store, depending on your device.
Are there any fees associated with using Google Wallet?
Most transactions through Google Wallet are free, including sending money to friends and family. However, there might be fees for certain actions, such as using credit cards for transfers instead of bank accounts. Always review the fee structure within the app before proceeding with transactions.
Read About Google Wallet in Your Language

Google Wallet
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via google-payments@google.com, visit https://pay.google.com/about, or review their https://policies.google.com/privacy.










